Missing, lifted or creased shingles after a windstorm passed through your area.
Roof Insurance Claims in New Jersey and Pennsylvania
Storm damage on a roof is rarely obvious from the ground. We inspect, photograph and document the damage, meet your adjuster on site, and handle the claim through to the finished repair. That assistance costs you nothing.
Roofing
Siding
Gutters
Fascia & Soffit
Licensed & Insured
24/7 Emergency
Free Estimates
Claims Assistance
We Handle the Claim So You Do Not Have To
Most homeowners file one roof claim in their life, which means learning the process at the worst possible moment. Expert Home Construction INC has handled storm claims for fifteen years in New Jersey and Pennsylvania, and that experience is what the first week of a claim runs on.
If wind, hail or a storm damaged your roof, the damage may be covered under your policy. Whether it is covered depends on your policy and on what the adjuster finds, and nobody can promise an outcome before an inspection has happened.
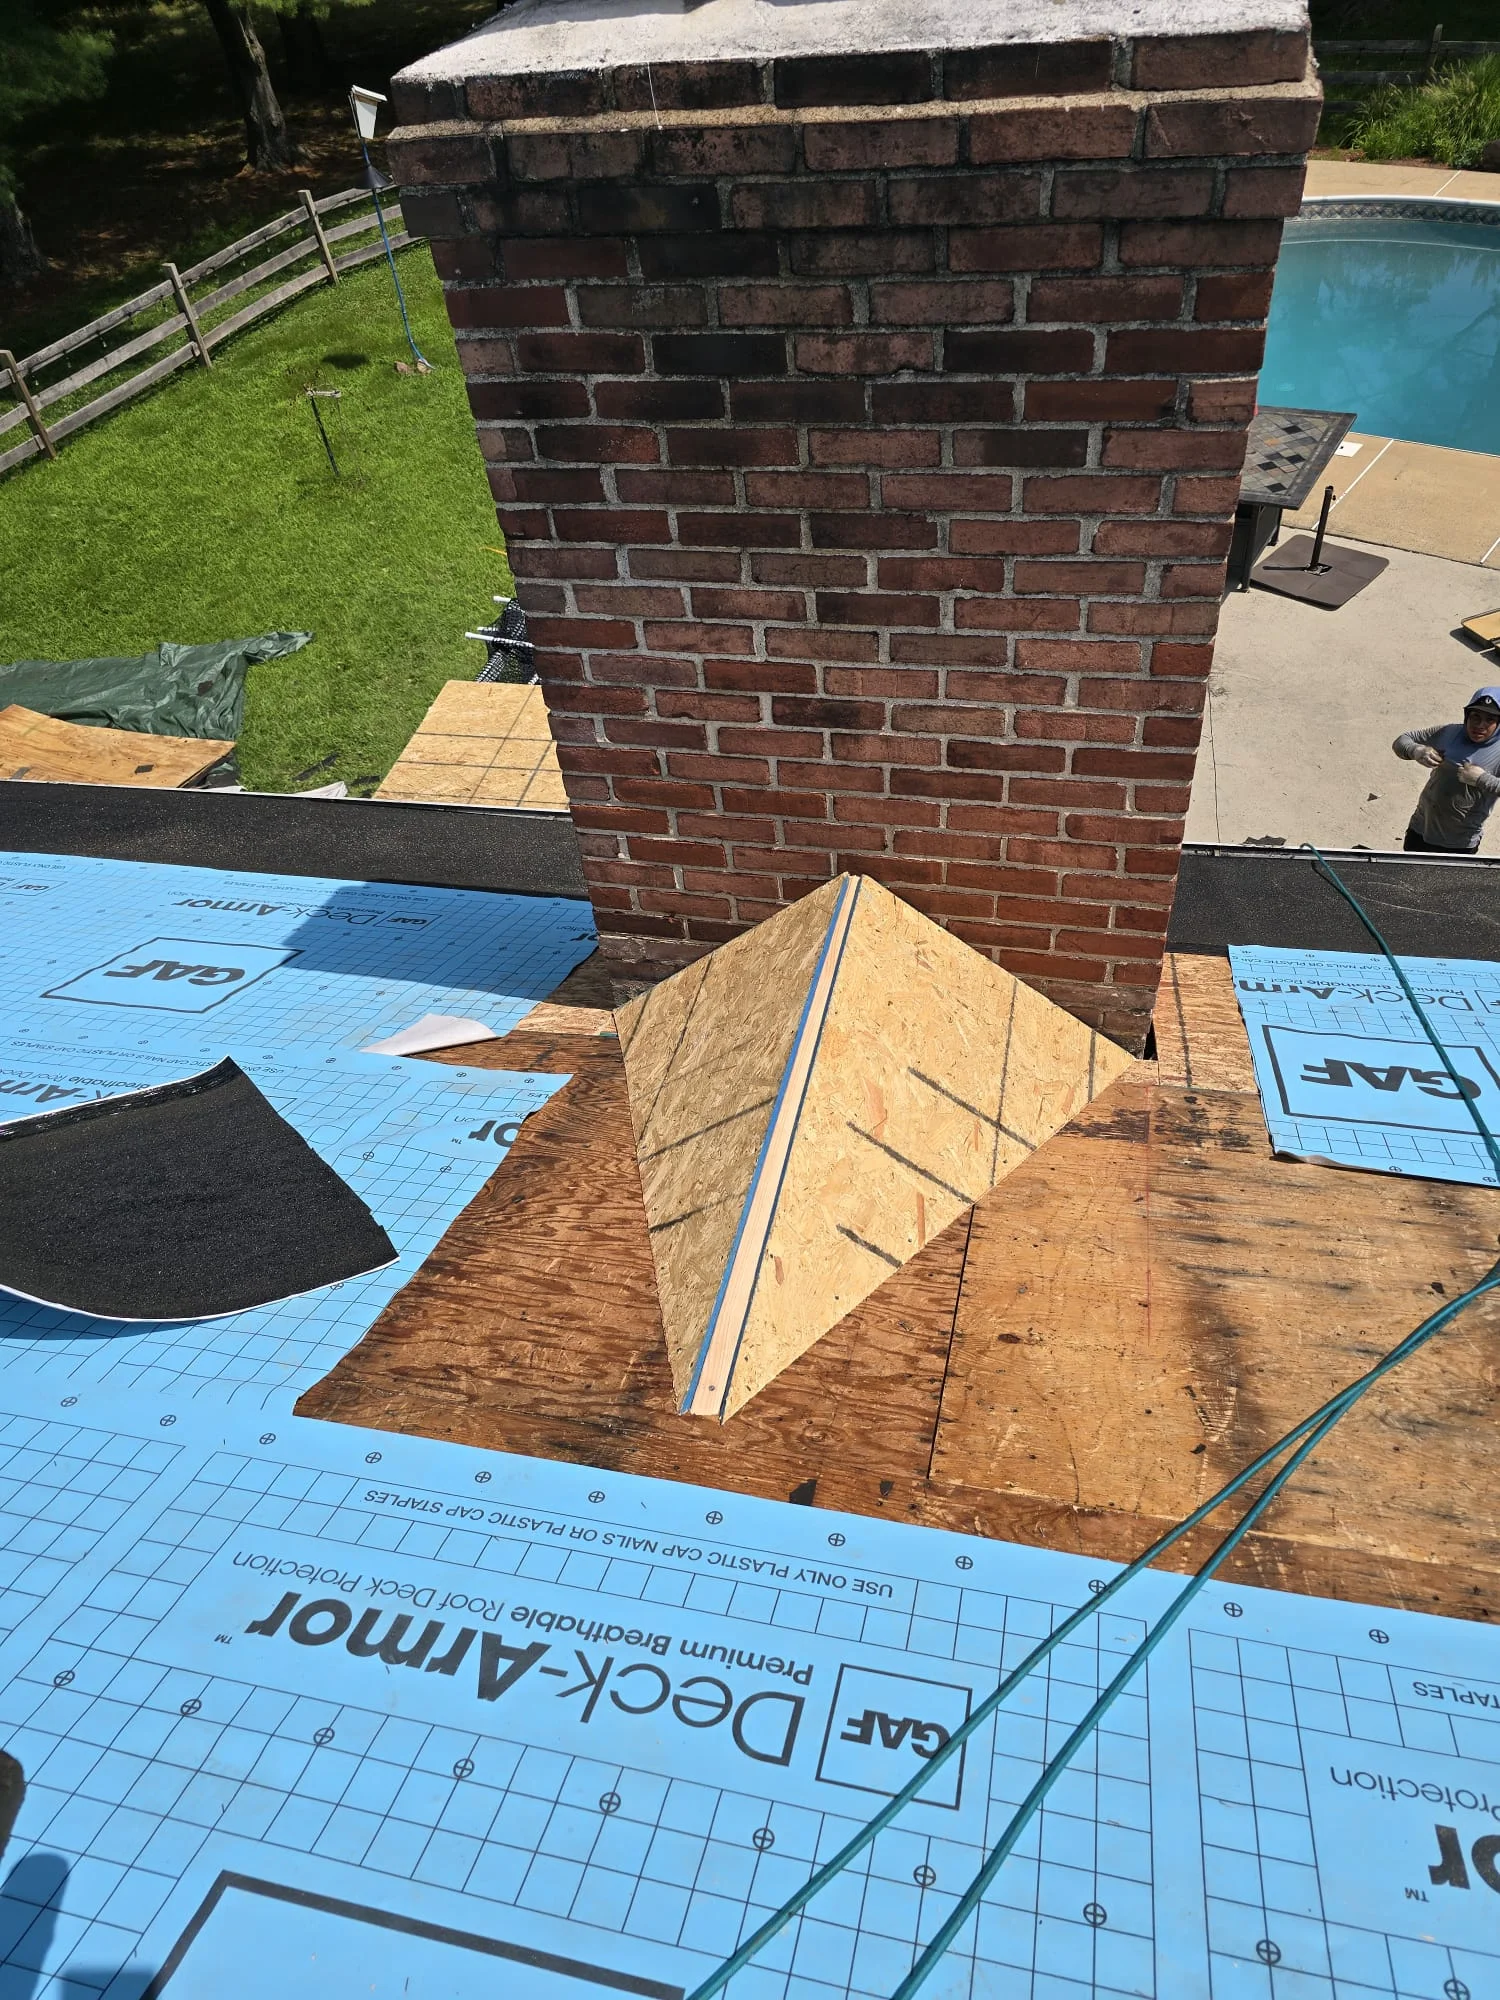
15
Years of Storm Claim Experience
Do You Qualify?
Signs Your Roof May Have Claimable Storm Damage
These are the signs worth an inspection. Finding them does not guarantee coverage, and missing them does not rule it out.
Hail marks on shingles, vents, flashing or the metal on your gutters.
Water stains on ceilings or walls that appeared after a specific storm.
Granules collecting in the gutters or at the bottom of your downspouts.
Fallen branches or debris that struck the roof during a recent storm.
Damaged flashing, vents or ridge caps visible from the ground after wind.
Not sure? The inspection is free and it tells you what is actually there.
How It Works
The Claim Process, Step by Step
-
1
Free Roof Inspection
We inspect the roof and the attic for storm damage, then photograph and date everything found before anything is touched, repaired or cleared away.
-
2
Claim Filing Guidance
You file the claim with your carrier. We explain what to report, what documentation matters, and what the carrier will ask you for first.
-
3
Adjuster Meeting
We meet your adjuster on site so both parties are looking at the same damage. That single step prevents most disagreements before they start.
-
4
Scope Review
Once the carrier issues a scope, we review it against what the repair actually requires and explain in plain terms where the two differ.
-
5
Roof Repair or Replacement
Once you approve, the work gets scheduled and completed. Emergency tarping happens on day one, well before any of this paperwork is resolved.
-
6
Final Documentation
You receive the completed paperwork the carrier needs to release final payment, along with photos of the finished work for your own records.
No Cost to You
What Is Included at No Cost to You
Full roof inspection with dated photographs of all damage found.
Written scope describing exactly what the repair work requires.
Adjuster meeting on site, with our crew present throughout.
Review of the carrier scope against the actual repair needed.
Emergency tarping the same day, before the claim is resolved.
Final paperwork and completion photos for your own records.
Your Options
Not Every Roof Goes Through Insurance
Some damage is covered, some is not, and some roofs are simply old. We tell you which one you are looking at.
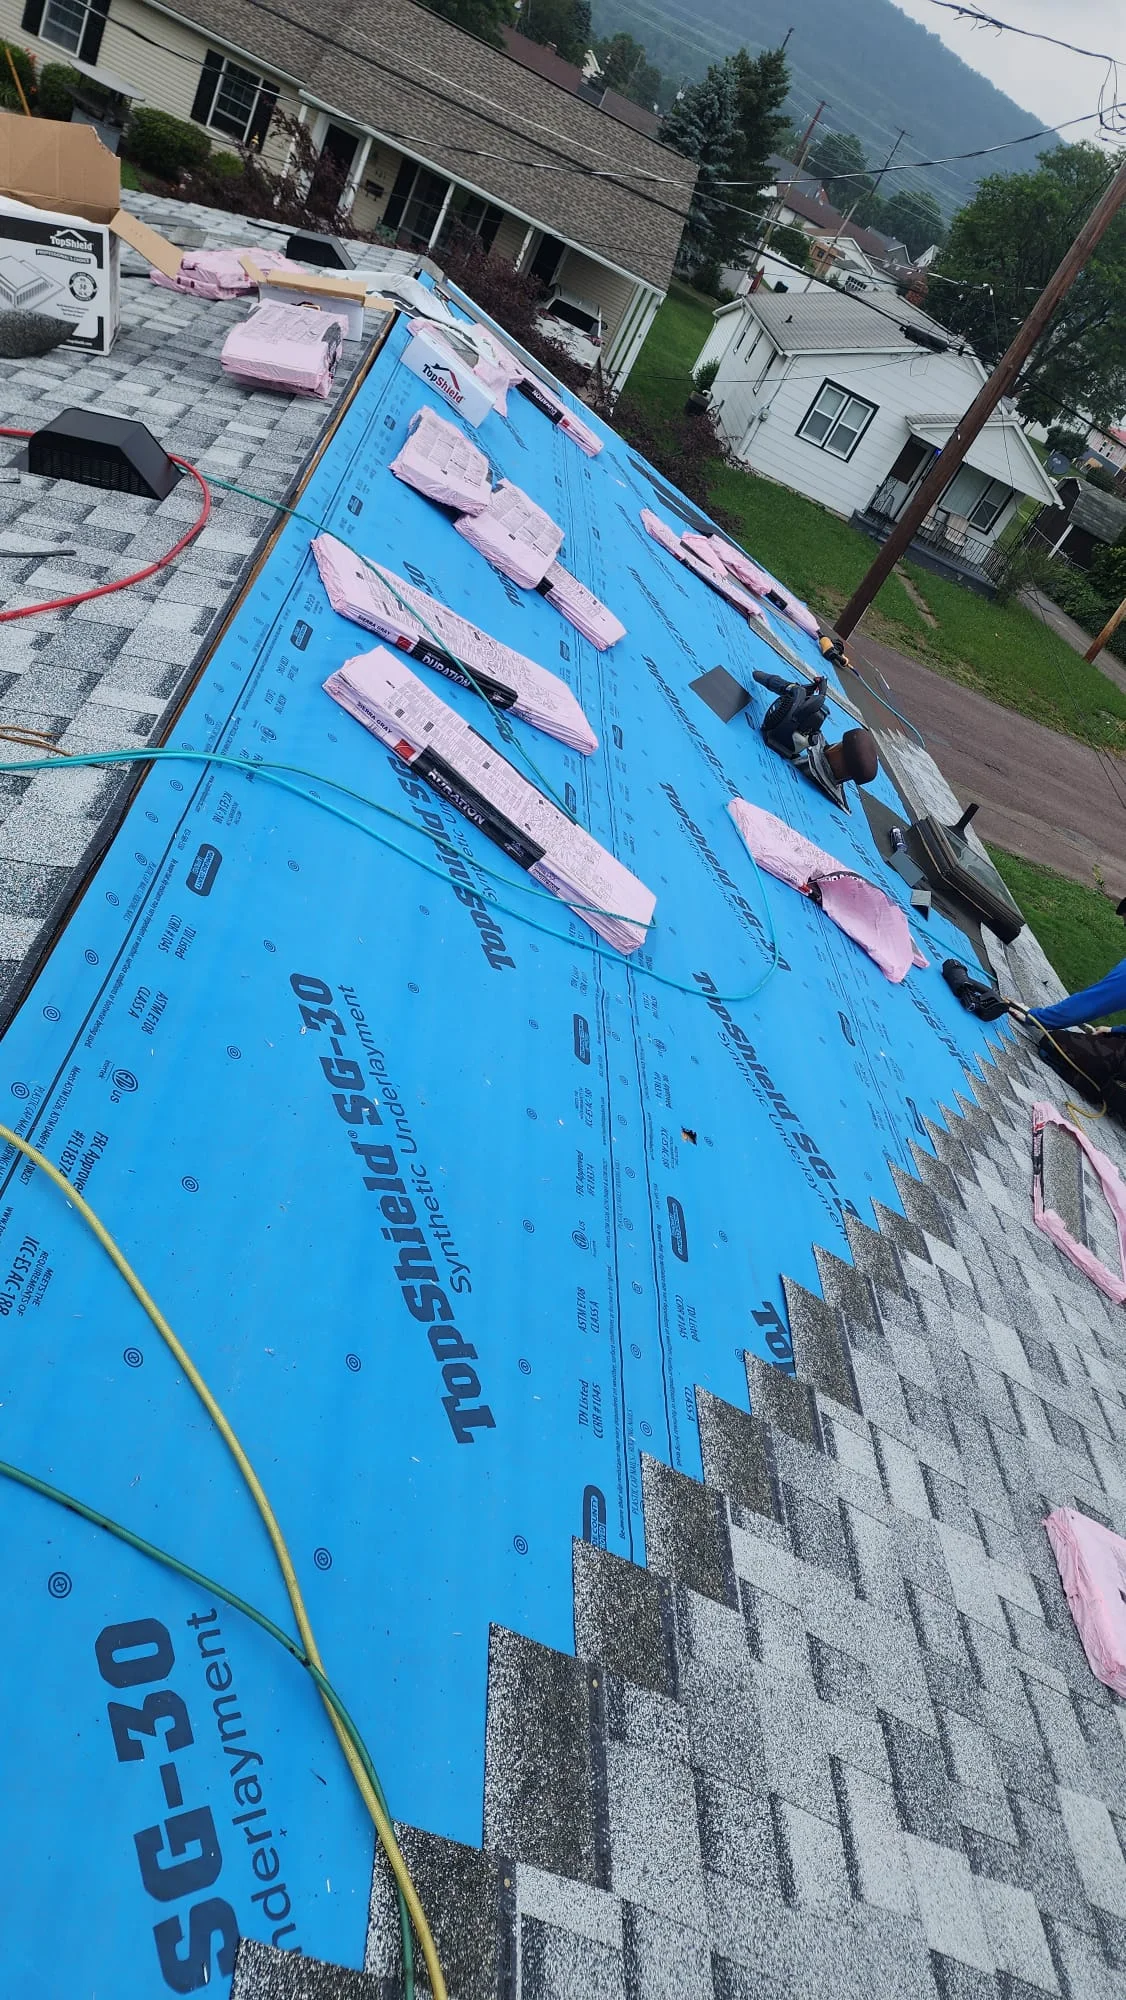
Insurance Claims
Storm damage from a covered event, documented and taken through the full claim process with your carrier, from the first inspection to final paperwork.
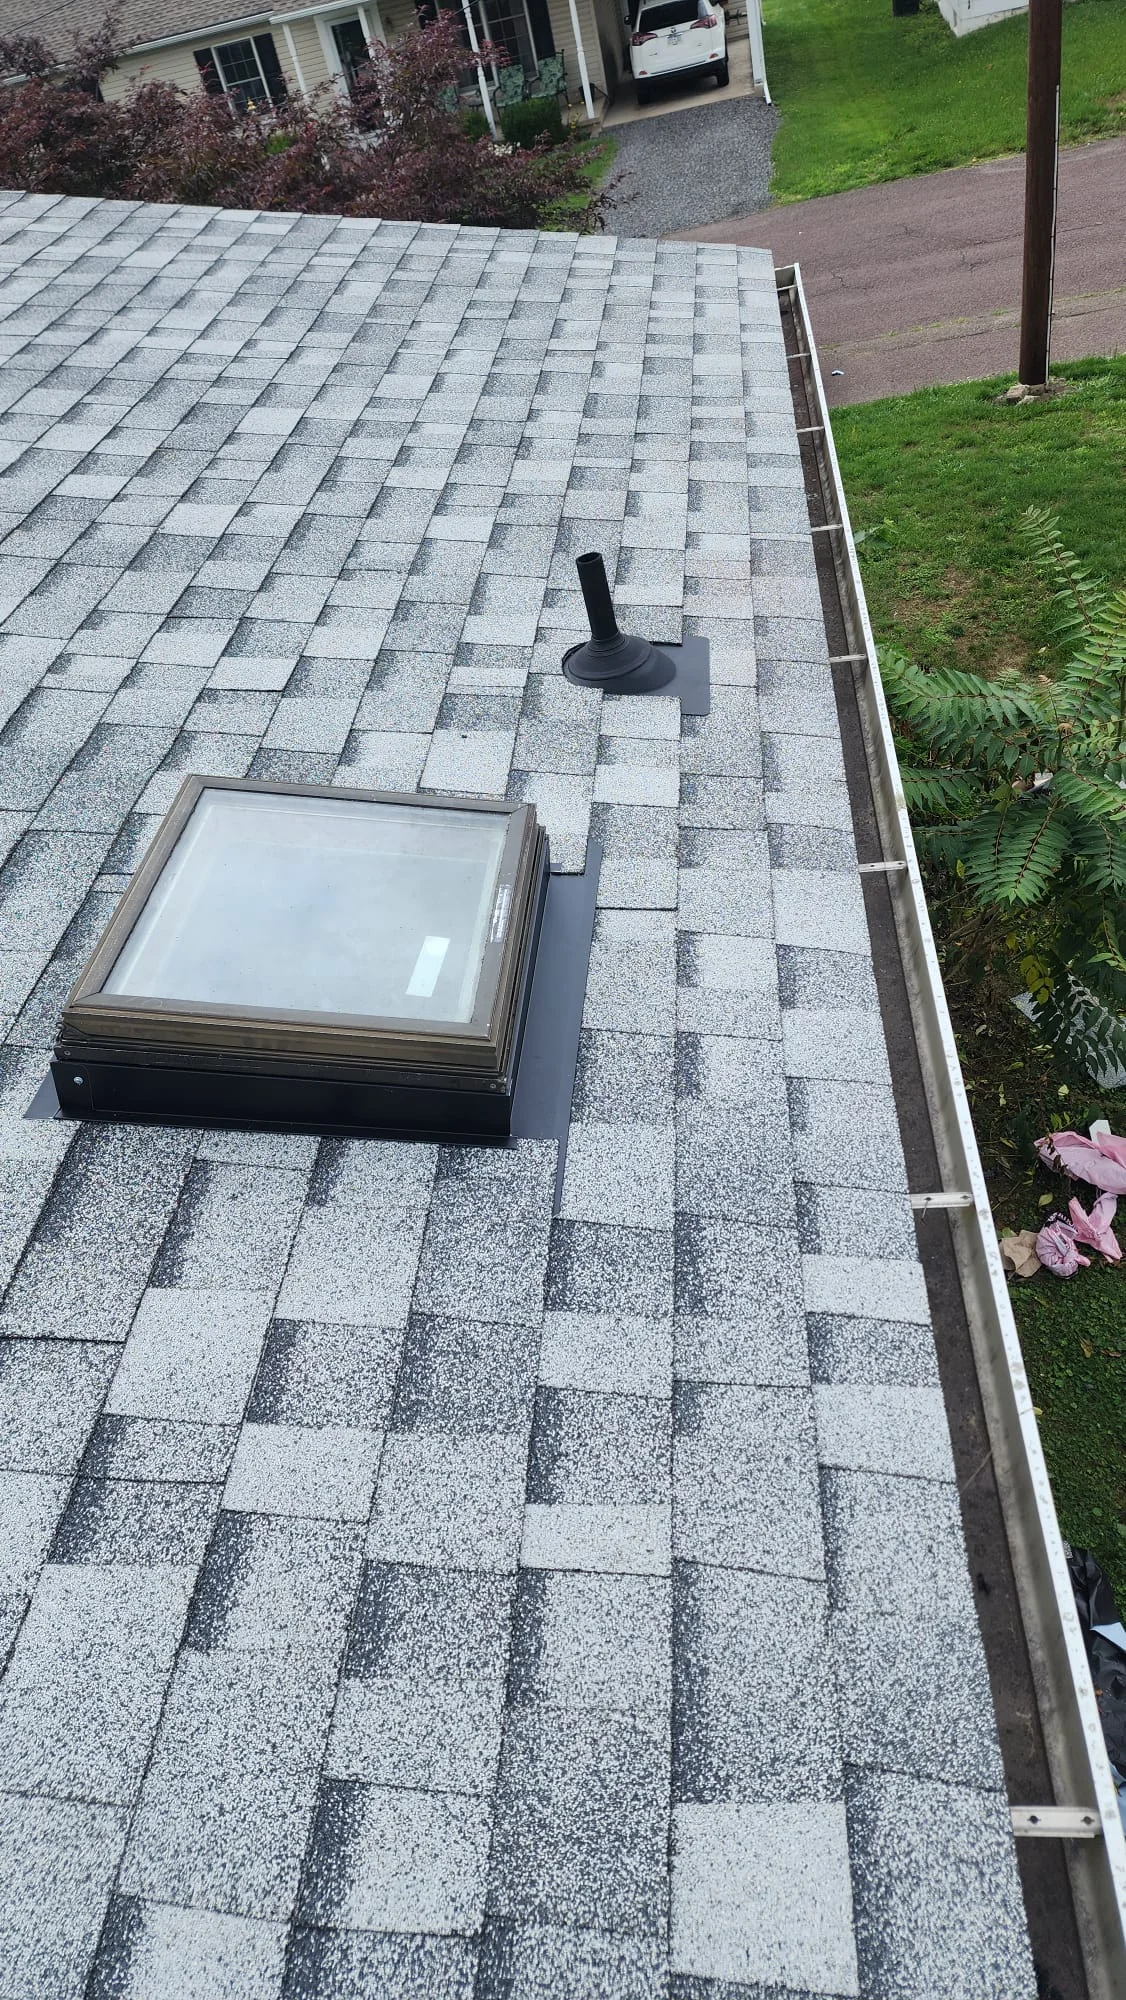
Direct Projects
Replacements and repairs paid directly, with written pricing up front. Roof financing through GoodLeap is available so the full cost does not land at once.
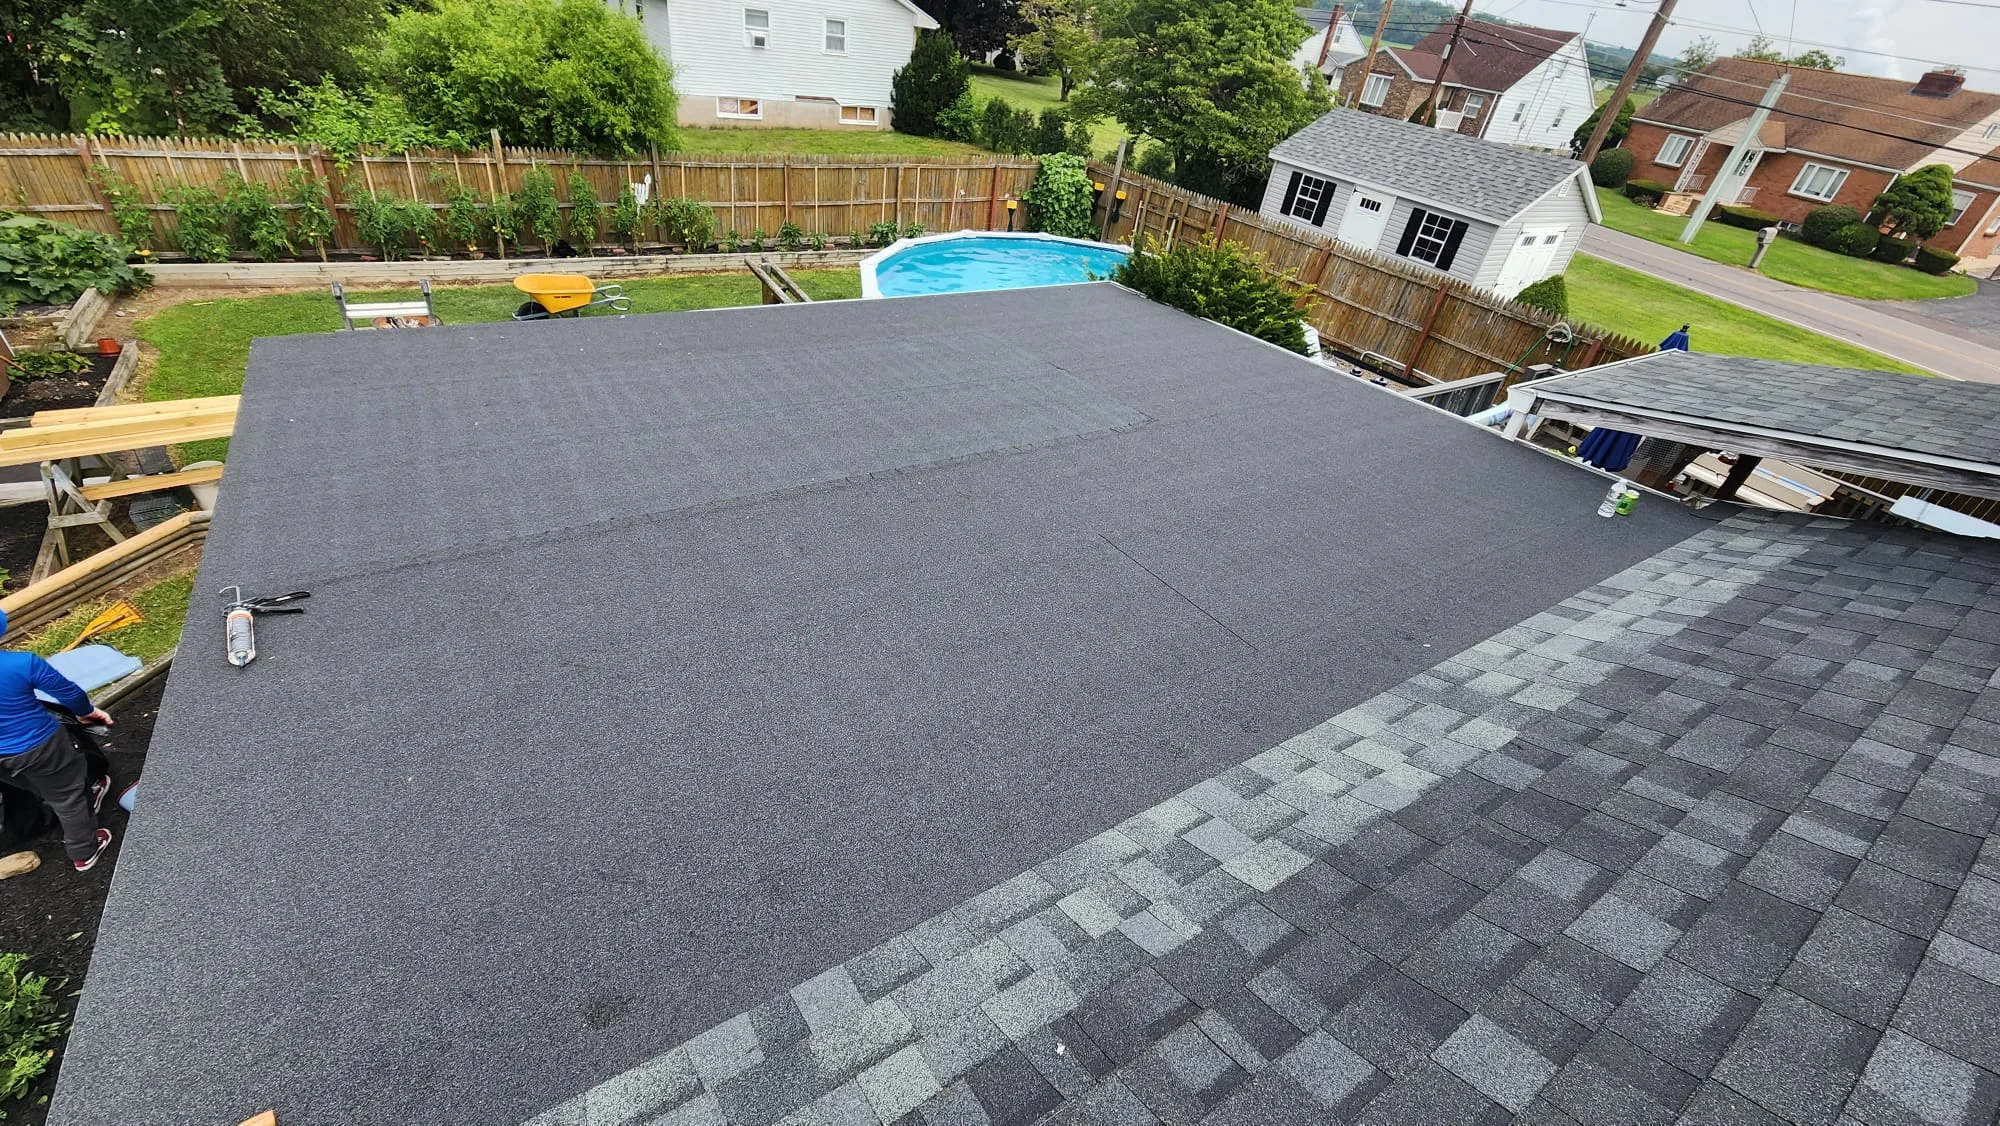
Partial Repairs
When only a section is damaged and the rest of the roof is sound, a repair is the honest answer and that is what gets recommended.
Good to Know
Roof Insurance Claim Questions
Does insurance always cover a storm damaged roof?
No. Coverage depends on your policy and on whether the damage came from a covered event. Age and wear are generally excluded. The inspection tells you what is actually there before you file.
How long do I have to file a roof claim?
Policies vary and most require prompt notice. Sooner is always stronger. A claim filed months after the storm invites the argument that the damage came from something else entirely.
What does the claims assistance cost me?
Nothing. The inspection, the documentation, the written scope and the adjuster meeting are all included. You pay for the roof work, and only after you have approved it.
Will filing a claim raise my premium?
It can, and it depends on your carrier, your claims history and whether the storm was a widespread regional event. Your agent can answer that better than any roofer can.
Do I have to use the contractor my insurer suggests?
No. You choose who does the work. The insurer decides what is covered, not who holds the hammer.
Can you cover or discount my deductible?
No, and you should walk away from any contractor who offers to. Absorbing or rebating a deductible is insurance fraud, and it puts the homeowner at risk as much as the contractor.